April 20, 2026

Oil Prices, Jobs, and Mortgage Rates: Key Housing Market Trends in 2026

3 Economic Numbers Shaping the Housing Market Right Now

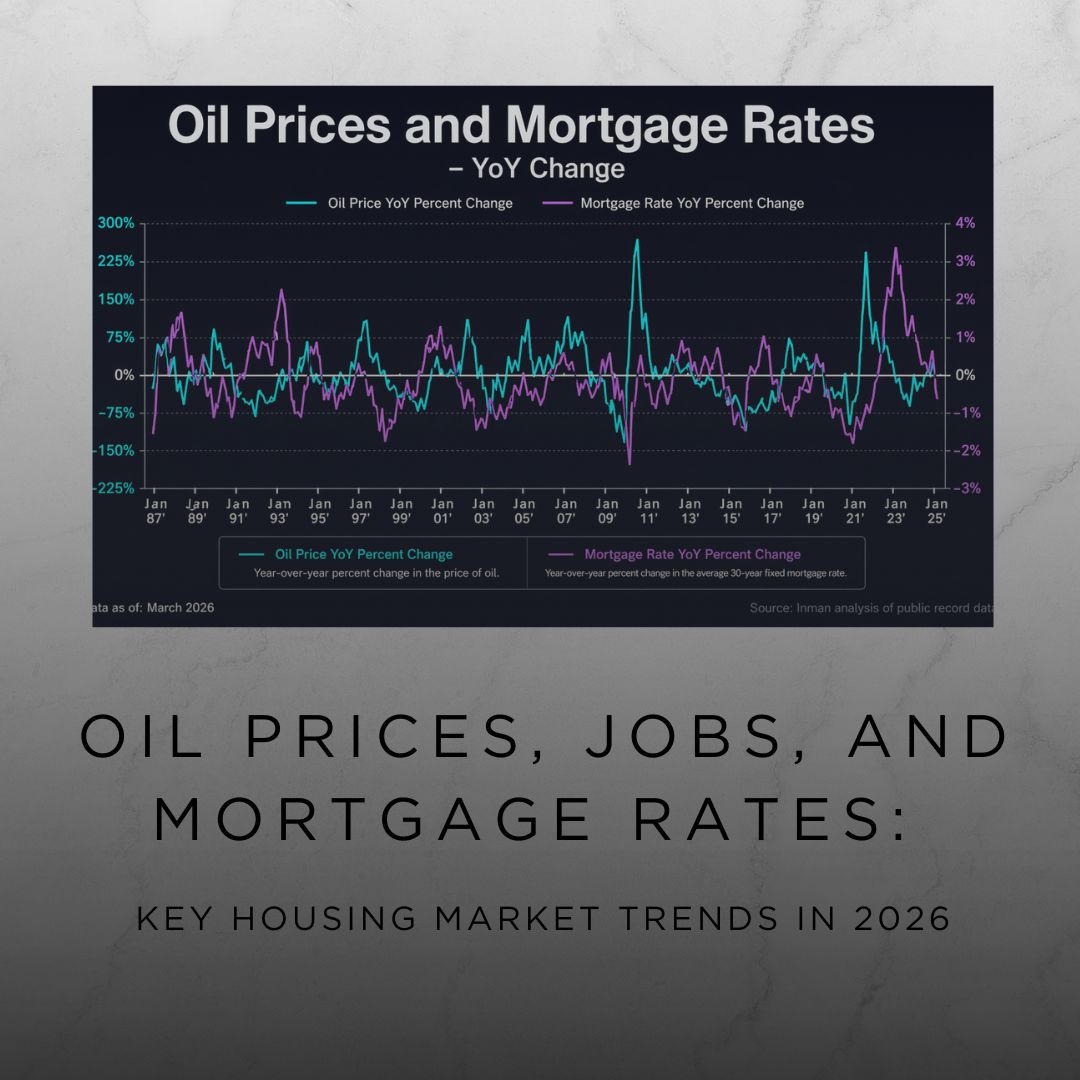
If you’re trying to understand where the housing market is headed in 2026, three key economic indicators are telling the story: oil prices, job growth, and mortgage rates. Together, these factors are influencing affordability, buyer demand, and overall market conditions.

1. Oil Prices Are Driving Inflation

One of the biggest shocks to the economy this year has been the sharp rise in oil prices. A barrel of oil recently hit around $115—double what it was at the start of 2026. 

This spike is largely tied to ongoing geopolitical conflict, which is increasing the cost of energy worldwide. Higher oil prices don’t just impact gas—they raise the cost of producing and transporting goods, contributing to inflation across the economy. 

For the housing market, this matters because inflation often leads to higher interest rates, making borrowing more expensive.

2. Job Growth Is Strong—but Uncertain

The labor market showed strength in March, with 178,000 jobs added, marking one of the strongest months for job growth in over a year. 

However, the broader trend tells a more complicated story. Over the past year, job gains have been inconsistent, with noticeable swings between growth and decline. 

This mixed signal is important because a strong job market gives the Federal Reserve less urgency to lower interest rates. In other words, as long as employment remains stable, borrowing costs—including mortgage rates—may stay elevated.

3. Mortgage Rates Remain Elevated

Mortgage rates are currently hovering around 6.5%, after rising from earlier lows in 2026. 

This increase is closely tied to inflation and economic uncertainty. As rates climb, affordability declines, making it harder for buyers to enter the market—especially during what is typically the busy spring season. 

Higher rates are already slowing buyer demand, leading to a more balanced housing market rather than the competitive conditions seen in recent years.

4. Housing Inventory Is Increasing

Another important trend is the rise in available homes. There were about 964,000 active listings at the end of March, representing an 8% increase compared to last year. 

This increase in inventory could benefit buyers by giving them more options and negotiating power. However, it also means sellers need to be more competitive in pricing and presentation.

What This Means for Buyers and Sellers

  • Buyers: More inventory may create opportunities, but higher mortgage rates could limit affordability
  • Sellers: Increased competition means pricing and presentation matter more than ever
  • Market Outlook: The housing market is shifting toward balance, driven by broader economic forces

The Bottom Line

The housing market in 2026 isn’t being shaped by one single factor—it’s the combination of rising oil prices, a resilient but uneven job market, and elevated mortgage rates. These forces are working together to create a more balanced (and slightly more challenging) environment for both buyers and sellers.

Understanding these key numbers can help you make smarter real estate decisions in a rapidly changing market.


Source: Adapted from reporting by Inman

Posted in Market Updates
April 16, 2026

Foreclosures Are Rising in 2026: What It Means for the Housing Market

The U.S. housing market is showing new signs of strain as foreclosure activity rises in early 2026. According to recent data, foreclosure filings increased significantly in the first quarter of the year, suggesting that some homeowners may be feeling growing financial pressure.

In Q1 2026, more than 118,000 properties across the United States had foreclosure filings. That marks a noticeable increase compared to both the previous quarter and the same time last year. These filings include default notices, scheduled auctions, and bank repossessions—all indicators that homeowners are struggling to keep up with mortgage payments.

One of the most important warning signs is the rise in foreclosure starts, which jumped by about 20% year-over-year. This suggests that more homeowners are entering the early stages of foreclosure, often due to missed payments or financial hardship. At the same time, bank repossessions surged even more dramatically—up 45% from last year, indicating that more cases are reaching completion. 

What’s Driving the Increase?

While foreclosure levels are still below the peaks seen during past housing crises, the upward trend points to broader economic pressures. Rising living costs, higher mortgage rates, and overall affordability challenges are making it harder for some homeowners to stay current on their loans. 

This doesn’t necessarily mean a housing crash is imminent. In fact, many experts view this increase as part of a “normalization” process following historically low foreclosure activity in recent years. However, the steady rise does suggest that financial stress is building for certain segments of the population.

Where Are Foreclosures Happening Most?

Foreclosure activity is not evenly distributed across the country. States like Florida, Texas, California, and Illinois are seeing some of the highest numbers of foreclosure starts. Additionally, certain metro areas—including large cities—are experiencing higher concentrations of filings, reflecting local economic conditions and housing affordability challenges.

What This Means for Buyers and Sellers

For buyers, rising foreclosures could eventually create more opportunities in the housing market, potentially increasing inventory and offering lower-priced options. For sellers and homeowners, however, the trend is a reminder of the importance of financial planning and staying ahead of mortgage obligations.

The Bottom Line

The increase in foreclosure activity in 2026 is worth paying attention to, but it doesn’t necessarily signal a crisis. Instead, it reflects a shifting market where economic pressures are beginning to impact some homeowners. As the year continues, watching foreclosure trends will be key to understanding where the housing market is headed next.


Source: Adapted from reporting by Realtor.com

Posted in Market Updates
April 5, 2026

2026 Housing Market Shift: Why Home Sales May Not Surge After All (And What It Means for Buyers & Sellers)

The 2026 Housing Market Isn’t Playing Out Like Experts Expected

At the start of the year, the National Association of Realtors (NAR) projected a strong rebound in home sales—some forecasts even called for a double-digit increase.

But now? That outlook is shifting.

According to a recent report from Inman article on NAR forecast shift, NAR is pulling back on those expectations due to one major factor:

👉 Mortgage rate volatility


What’s Actually Happening with Mortgage Rates?

Mortgage rates have been… unpredictable (and honestly, a little dramatic).

  • Rates hovered near 7% in early 2025
  • Dropped closer to 6% in 2026
  • Even briefly dipped below 6%—a major psychological win for buyers 

But here’s the problem:
They’re not stable.

And in real estate, uncertainty = hesitation.

When rates bounce around, buyers pause. Sellers hesitate. Deals slow down.


Why Home Sales Are Being Reined In

Even though affordability has slightly improved, the market isn’t taking off like expected.

Here’s why:

1. Buyers Are Still Payment-Sensitive

Even a small rate change can mean hundreds of dollars per month difference

So instead of rushing in, buyers are:

  • Waiting 
  • Watching 
  • Trying to “time” the market (spoiler: risky move) 

2. The “Lock-In Effect” Isn’t Fully Gone

Many homeowners are still sitting on ultra-low rates from 2020–2022.

Translation:
👉 They don’t want to sell and take on a higher rate.

That keeps inventory tighter than normal.


3. Economic & Global Uncertainty Is Creeping In

Things like inflation concerns, geopolitical tension, and oil prices can impact mortgage rates quickly 

And when consumers feel uncertain, they don’t make big financial moves.


But Here’s the Plot Twist (And Opportunity 👀)

This is NOT a crash.

It’s a rebalancing.

  • Prices are still holding (even increasing modestly) 
  • Inventory is slowly improving 
  • Affordability is better than last year 

👉 We’re moving from chaos → strategy


What This Means for Buyers in 2026

If you’re buying, this market actually gives you leverage you didn’t have 2–3 years ago:

  • Less competition 
  • More negotiating power 
  • Potential seller concessions 
  • Ability to refinance later if rates drop 

💡 Translation: You don’t need perfect timing—you need a smart strategy.


What This Means for Sellers

Let’s be honest (because I always am):

You can still win—but not by winging it.

Today’s sellers need:

  • Strategic pricing (not “let’s test it high and pray”) 
  • Strong marketing 
  • A dialed-in agent who knows how to position your home 

Because buyers?
They’re picky again.


The Bottom Line

The 2026 housing market isn’t crashing… it’s correcting expectations.

NAR expected a surge.
Instead, we’re getting something healthier:

👉 A more balanced market
👉 More intentional buyers
👉 Smarter decisions on both sides

And honestly?
That’s where the best deals happen.


Thinking About Buying or Selling in Columbus?

Whether you’re trying to time the market or just figure out your next move—let’s map out a strategy that actually makes sense for you.

📩 Message me for a custom home value or buying plan


SOURCE

This article references reporting from Inman News and data from the National Association of Realtors (NAR) regarding 2026 housing forecasts and mortgage rate trends.

Posted in Market Updates
March 17, 2026

Why Mortgage Rates Move (And What It Means for Homebuyers in Columbus, Ohio)


Why Mortgage Rates Move (And What It Means for Homebuyers in Columbus, Ohio)

Meta Description:
Wondering why mortgage rates change so often? Learn the key factors that influence mortgage rates and what they mean for homebuyers in Columbus, Ohio.


Why Do Mortgage Rates Move So Much?

If you’ve been watching mortgage rates lately, you’ve probably noticed they don’t move in a straight line. One week they drop, the next week they climb again.

Understanding why mortgage rates change can help buyers make smarter decisions about when to purchase a home.

Recently, mortgage rates briefly dipped below 6% before climbing back above that level due to changes in inflation expectations and economic data. 

But the truth is: mortgage rates aren’t controlled by one single factor.They respond to a combination of economic forces happening behind the scenes.

Let’s break down the biggest ones.


1. Inflation: The Biggest Driver of Mortgage Rates

Inflation is one of the most important forces affecting mortgage rates.

When inflation rises, lenders demand higher interest rates to compensate for the fact that money will be worth less in the future. 

For example:

  • Higher gas prices
  • Rising consumer prices
  • Increasing wage growth

These signals can push inflation expectations higher, which often pushes mortgage rates higher as well. 

When inflation cools, mortgage rates tend to ease.


2. The 10-Year Treasury Bond

Most people think the Federal Reserve directly sets mortgage rates, but that’s not exactly how it works.

Mortgage rates tend to follow the 10-year U.S. Treasury yield, which acts as a benchmark for long-term borrowing costs. 

When Treasury yields rise:

➡ Mortgage rates usually rise.

When Treasury yields fall:

➡ Mortgage rates usually fall.

Lenders typically price a mortgage as the 10-year Treasury yield plus an additional spread to cover risk and costs. 


3. The Federal Reserve (Indirectly)

The Federal Reserve does not directly set mortgage rates, but its policies influence them.

When the Fed raises short-term interest rates to slow inflation, it often pushes bond yields higher, which eventually leads to higher mortgage rates. 

When the Fed cuts rates to stimulate the economy, mortgage rates may drift downward.

However, the relationship isn’t always immediate or predictable.


4. The Overall Strength of the Economy

Strong economic data can also cause mortgage rates to rise.

If the economy is growing quickly, with strong job growth and consumer spending, investors may expect inflation to remain elevated. 

That expectation can push long-term interest rates higher.

On the flip side, when the economy slows, investors often move money into safer assets like bonds, which can pull mortgage rates down.


5. Global Events and Market Sentiment

Mortgage rates are also influenced by global financial markets.

Things like:

  • International conflicts
  • Government policy changes
  • Stock market volatility
  • Global economic uncertainty

can all impact bond markets, which in turn affect mortgage rates.


What Mortgage Rates Mean for Homebuyers

Even small changes in mortgage rates can make a big difference in affordability.

For example, a 1% drop in mortgage rates can allow millions of additional households to qualify for a home loan because monthly payments become more manageable. 

That’s why buyers often rush back into the market when rates fall.


What This Means for the Columbus Housing Market

In Central Ohio, demand for homes remains strong, and mortgage rate movements can quickly influence buyer activity.

When rates dip:

  • More buyers enter the market
  • Competition increases
  • Homes may sell faster

When rates rise:

  • Some buyers pause their search
  • Negotiation opportunities increase

Understanding these trends can help buyers and sellers time their moves strategically.


Thinking About Buying or Selling in Columbus?

Mortgage rates are just one piece of the real estate puzzle. The right time to buy or sell often depends on your personal goals, timeline, and the local market conditions.

If you're curious about:

  • Current mortgage trends
  • Home values in your neighborhood
  • Buying or selling in Columbus

Reach out anytime.

👉 Search homes for sale in Columbus
👉 Get a free home value estimate

Or connect with me directly for a strategy tailored to your situation.


Posted in Market Updates
March 11, 2026

Columbus Ohio Housing Market Update: Lower Mortgage Rates Bring Buyers Back

Mortgage Rate and Buyer Demand


Lower Mortgage Rates Are Bringing Buyers Back Into the Market

The housing market continues to respond quickly to even small changes in mortgage rates. Recent data shows that when borrowing costs drop—even slightly—buyers are ready to jump back into the market.

According to the Mortgage Bankers Association, mortgage applications recently increased as buyers took advantage of temporarily lower interest rates. Purchase applications—those tied directly to homebuying—rose significantly, showing renewed demand from buyers who had been waiting on the sidelines.

This trend highlights something real estate professionals have been seeing firsthand: buyer demand is still strong, but many buyers are sensitive to mortgage rate changes.


What Lower Mortgage Rates Mean for Homebuyers

When mortgage rates dip, buying power improves.

Even a small decrease in interest rates can reduce a buyer’s monthly payment or allow them to afford a higher-priced home. Because of this, many buyers closely watch rate movements and jump into the market when favorable opportunities appear.

As we head further into the 2026 spring real estate market, small shifts in mortgage rates could continue to drive bursts of buyer activity.

For buyers in Columbus, Ohio and surrounding Central Ohio communities, this means competition may increase when rates drop and more buyers begin touring homes.


What This Means for Home Sellers in Columbus

If you're thinking about selling your home in Central Ohio, increasing buyer activity can work in your favor.

When more buyers enter the market, well-prepared homes often receive stronger interest and sometimes multiple offers. Homes that are updated, clean, and move-in ready tend to stand out the most.

Preparing your home before listing can help maximize its value when buyer demand increases.

Common improvements that make a big impact include:

  • Fresh interior paint

  • Updated lighting

  • Minor cosmetic repairs

  • Decluttering and staging

  • Improving curb appeal

Many of these upgrades are relatively affordable but can significantly improve how buyers perceive a home during showings.


Preparing Your Home for the Spring Market

Spring is traditionally the busiest season in real estate, and early preparation can give sellers an advantage.

If mortgage rates remain stable or decline further, buyer demand could continue rising throughout the year. Homeowners who begin preparing their homes now will be in a strong position when the right buyer comes along.

If you're considering selling your home in Columbus, Dublin, Powell, Grove City, or surrounding Central Ohio communities, understanding market trends and preparing your home properly can make a major difference in your final sale price.

Posted in Market Updates
Feb. 16, 2026

The Annual Reset Your Home Deserves

Most people only prepare their home like it’s “for sale” when they’re actually moving.

I believe you should do it once a year—whether you’re selling or not.

Not for the market.
Not for listing photos.
Not for strangers walking through your space.

For you.

There’s something transformative about the way we prepare a home to sell. We declutter ruthlessly. We deep clean every corner. We fix the things we’ve been putting off. We simplify and style with intention. We make it feel calm, open, and inviting.

And then… we leave.

But what if we stopped waiting for a move to experience that feeling? What if “move-in ready” became your everyday standard instead of a temporary phase?

Create Your Own Annual “Open House”

Once a year, set aside a weekend and walk through your home as if you’re seeing it for the first time. Slow down. Stand in each doorway. Notice what feels peaceful—and what feels overwhelming.

Then take action.

Declutter with intention.
Go drawer by drawer. Closet by closet. Surface by surface. Clear off countertops. Edit bookshelves. Simplify entryways. If you wouldn’t want it on display during a showing, ask yourself why it’s on display now.

Take care of the small repairs.
The loose door handle. The scuffed baseboards. The wobbly shelf. The chipped paint. These tiny unfinished tasks create quiet visual stress. Finishing them brings a surprising sense of closure.

Deep clean beyond your usual routine.
Wipe down trim and doors. Clean vents and light switches. Wash windows and windowsills. Dust the places you normally skip. A truly clean home feels different.

Refresh what feels tired.
Touch up paint. Rearrange furniture for better flow. Remove a few decorative items instead of adding more. Create breathing room.

Evaluate how your home functions.
Is there a space that feels chaotic? A corner that’s become a drop zone? A room that’s forgotten? Reclaim it.


The Result?

You create:

  • Less visual noise
  • Less to manage and maintain
  • More ease in your daily routines
  • A home that feels lighter and more intentional

You don’t need a new house to feel a fresh start.

Sometimes you just need to see your current home with new eyes—and care for it accordingly.

Treat your home like it matters.
Not when you’re leaving.
But while you’re living in it.


Posted in Home Tips
Feb. 13, 2026

Buyers Are Getting Creative: Why FHA Loans and ARMs Are Back in Focus


The housing market hasn’t exactly frozen — but it’s definitely not heating up.

With mortgage rates staying stubbornly high and home prices remaining elevated in many markets, buyers are adjusting their strategies. Instead of waiting around for dramatic rate cuts, many are exploring alternative financing options that can make homeownership feel more attainable right now.

Two loan types are standing out: FHA loans and adjustable-rate mortgages (ARMs).

FHA Loans: A Practical Path for Today’s Buyers

FHA loans have long been popular with first-time buyers, but they’re gaining even more attention in today’s market. Why? Lower down payment requirements and more flexible credit guidelines make them an accessible option — especially for buyers who are stretched by higher monthly payments.

In a high-rate environment, even a small difference in interest rate or upfront cost can make a meaningful impact on affordability. That’s pushing more borrowers to consider FHA financing as a way to stay competitive without overextending financially.

ARMs: Short-Term Strategy in a Long-Term Market

Adjustable-rate mortgages are also making a comeback. ARMs typically offer a lower introductory interest rate for the first several years of the loan. For buyers who expect to refinance, relocate, or increase their income before the adjustment period kicks in, this can be a strategic move.

Of course, ARMs aren’t for everyone. The rate adjustment later on carries risk, so borrowers need to understand the long-term implications. But in today’s market, some buyers are deciding that short-term savings outweigh long-term uncertainty.

What This Signals About the Market

When buyers shift toward FHA loans and ARMs, it tells us one thing clearly: affordability is driving decisions.

Instead of stepping out of the market entirely, buyers are adapting. They’re weighing options, calculating risk, and choosing financing structures that align with their financial reality.

The takeaway? The mortgage market may feel stagnant, but buyers are far from inactive. They’re simply being strategic — and lenders and real estate professionals need to be prepared to guide them through these evolving choices.

Source: Homes.com


Posted in Market Updates
Feb. 11, 2026

Why Home Sales Are Canceling: The Real Reasons Behind the 16.3% Record-High in 2026

Why Home Sales Are Canceling: The Real Reasons Behind the 16.3% Record-High in 2026

Home sales aren’t canceling because people suddenly stopped wanting homes.

They’re canceling because the math stopped working.

In late 2025 heading into 2026, 16.3% of home purchase contracts were canceled — the highest rate since tracking began. That’s not a fluke. That’s a signal. And the reasons go deeper than “bad inspections” or “cold feet.”

Here’s what’s actually causing deals to fall apart.


1. Buyers Are Hitting the Payment Wall

This is the biggest driver — and the one nobody likes to admit.

Buyers are getting into contract emotionally…
…and backing out financially.

When they sit down with:

  • mortgage payments

  • property taxes

  • insurance

  • utilities

  • maintenance

…the monthly number hits different.

So the inspection becomes the socially acceptable exit ramp. Not because the house is unlivable — but because the payment is.

Translation: affordability is killing deals, not drywall cracks.


2. Inspections Are No Longer About Repairs — They’re About Leverage

Inspections used to answer:

“Is this house safe?”

Now they answer:

“Do I still want this deal at this price and rate?”

When sellers outnumber buyers, inspections become negotiation weapons. Even small issues become reasons to demand credits, price cuts, or walk.

Not because the issue is catastrophic — but because buyers finally can.


3. Sellers Are Anchored to Yesterday’s Prices

Sellers are still mentally living in 2021–2022.

Buyers are living in 2026 interest rates.

That gap is the standoff.

When sellers refuse to adjust:

  • price

  • repair credits

  • closing costs

…buyers cancel. Not out of spite — out of logic.

Deals die when expectations don’t meet reality.


4. Buyers Now Have Options (And That Changes Behavior)

In low-inventory markets, buyers tolerate bad terms.

In higher-inventory markets, buyers don’t tolerate nonsense.

When buyers know:

  • another house will come

  • another seller will negotiate

  • another deal will exist

…they walk faster.

Scarcity created desperation.
Choice creates standards.


5. Financing Is Exposing Weak Buyers Late in the Process

Pre-qualifications aren’t saving deals anymore.

Underwriting is.

A huge chunk of cancellations happen when:

  • appraisals come in low

  • debt ratios fail

  • documentation gets real

  • rate locks expire

  • payments spike

By the time buyers reach this stage, backing out feels embarrassing — so inspections take the blame.


6. Sellers Are Withdrawing Instead of Adjusting

Many sellers would rather delist than admit the market shifted.

That creates:

  • repeated failed listings

  • contract fallout

  • price resistance

  • trust issues

When sellers won’t bend, buyers walk. Simple.

Pride is expensive in real estate.


7. The Market Is in a Psychological Reset

This is the big picture:

  • Buyers are recalibrating what “worth it” means

  • Sellers are recalibrating what “fair price” means

  • The market is in price discovery

  • Nobody feels comfortable yet

That discomfort shows up as cancellations.

This is what normalization looks like.
It’s messy. But it’s healthy.


🧠 Key Takeaways

  • Most cancellations are about affordability, not defects

  • Inspections are now exit strategies and leverage tools

  • Sellers anchoring to peak pricing are losing deals

  • Buyers with options walk faster

  • Financing realities are killing emotional decisions

  • The market is resetting expectations on both sides


🏁 Bottom Line

Home sales aren’t canceling because the market is broken.

They’re canceling because:

  • Buyers are thinking

  • Money is expensive

  • Sellers are slow to adapt

  • The market is re-learning balance

This is what a mature market looks like when reality punches the hype in the face.


📊 January 2026: Cancellation Trends — December vs. January

As record cancellation rates became one of the major storylines going into 2026, the behavior of those cancellations matters just as much as the numbers.

🇺🇸 National Cancellation Comparison

  • December 2025: Approximately 40,000 home-purchase agreements were canceled nationwide, equal to 16.3% of all homes that went under contract, the highest December cancellation rate on record since at least 2017. That’s up from 14.9% in December 2024, showing that fallout from purchase contracts increased year-over-year.
  • January 2026: While exact January cancellation rate figures haven’t been fully published yet by Redfin or other major data providers (which typically issue data releases after month-end processing), multiple housing market updates indicate that pending home sales activity slowed in early 2026 and buyers are remaining selective once contract terms start to matter — the underlying behavioral trend driving cancellations continues.

Bottom line:


The December spike (16.3%) wasn’t an isolated seasonal blip — it reflects buyers exercising leverage early in 2026, and signals that January activity is continuing under similar conditions of higher inventory, stronger buyer scrutiny, and affordability pressures.


📍 What This Means for Columbus in January 2026

While specific cancellation percentages for Columbus aren’t released independently of national data, related local metrics show the environment that contributes to deal fallout: 📈 Days on market in the Columbus metro have been extending, giving prospective buyers more time to evaluate and decide — including choosing to cancel when terms don’t align.
📊 The median Columbus price has softened on a trailing basis, and homes are selling more slowly than in peak years — conditions that give buyers leverage and confidence to back out of deals. Taken together with the national cancellation trend, this suggests that Columbus deals in January were more likely to see buyer hesitancy and contract revisits than in previous years, even if the exact cancellation percentage isn’t yet published.


🧠 Context: What’s Driving January Patterns

The December cancellation jump wasn’t random — it happened because: ✔ buyers have more choices and time to inspect their options
✔ sellers are still anchored to older pricing expectations
✔ mortgage rates are still higher than pre-2022 norms
✔ inspections and financing are being used as strategic exit points Those same dynamics haven’t disappeared in January — they’ve simply carried over into the new year. Pending sales being slower and homes staying on market longer are fertile conditions for cancellations as this trend continues into early 2026. 

📞 Call to Action 

If you’re buying or selling in 2026 and want to avoid becoming another canceled contract statistic, strategy matters more than speed.

👉 Browse Homes for Sale
👉 Get Your Home Value
👉 Talk to a Local Real Estate Expert

Posted in Market Updates
Feb. 11, 2026

Record High Home Purchase Cancellations in 2026: What It Means for Columbus, Ohio Buyers & Sellers

📉 Record High Home Purchase Cancellations & What It Means for the 2026 Columbus Market


Contract Cancellations Columbus Ohio


Based on the latest national data and local Columbus, Ohio housing stats — this is what buyers and sellers need to know right now.

Recent national housing data shows home purchase cancellations are at record highs, with roughly 16.3% of pending contracts falling out nationwide as of December 2025. This is the highest cancellation rate on record, and it’s reshaping buyer behavior and negotiation power in markets across the U.S. — including Central Ohio.

Here’s how this trend intersects with the Columbus, Ohio housing market in 2026.


🏡 Columbus Market by the Numbers (2025 → 2026)

Here’s the most up-to-date snapshot of Central Ohio:

📌 Median Home Sales Price:
• Central Ohio median home price hovered around $322,000 in December 2025, near seasonal lows.
• Redfin data places Columbus median sale price at about $270,000, down ~2.2% YoY.

📊 Inventory & Sales Activity:
• Inventory was ~4,440 homes in December, trending higher than last year — offering buyers more choices.
• Total closed home sales in 2025 topped 29,626, up ~3% from 2024.
• Columbus homes saw ~57 days on market, longer than last year — signaling softer competition.

📉 Price & Market Behavior:
• Some listings saw price reductions, and median list price dipped slightly.
• Month-to-month price trends stabilized as inventory grew — a shift from previous years of rapid appreciation.


📊 What Rising Cancellations Mean for Central Ohio

🧠 For Buyers

1. More Leverage = Better Negotiation
With more active listings and longer days on market, Columbus buyers can be selective. You’re not forced into frenzied bidding wars, giving you a chance to negotiate price, inspection terms, and closing timelines.

2. Shopping Around Isn’t Weak — It’s Smart
National cancellation rates are inflating as buyers don’t fear walking away. In Central Ohio’s stabilized market, this means buyers can actually walk on deals that don’t pass inspection or don’t appraise. That’s leverage you didn’t have a few years ago.

3. Get Rock-Solid Financing
Deals commonly fall through due to financing issues. A full pre-approval (not just pre-qualification) will keep you front-of-line when the right home hits the market.


📈 For Sellers

1. Competition Matters
More inventory means more homes for buyers to choose from — just because homes were flying off shelves doesn’t mean they automatically will in 2026. Pricing right and staging professionally is critical.

2. Inspections & Transparency Win Deals
Cancellations are often driven by inspection surprises. Posting clean inspection reports upfront turns uncertainty into confidence.

3. Expect Longer Escrows + Win Strategically
Buyers who are cautious are going to ask for contingencies and more time — that’s not a sign of weakness, it’s a reflection of market conditions. Good agents negotiate these so deals stay intact.


📌 Columbus Market Trends to Watch in 2026

  • Inventory growth is giving buyers options and softening competition slightly compared to classic seller-favored markets.

  • Median prices have stabilized (not runaway increases), offering a more predictable decision landscape for buyers and sellers alike.

  • Days on market are trending longer, meaning unprepared sellers risk deals languishing or falling through.


🏁 Bottom Line

The 2026 housing market in Columbus is not crashing — it’s balancing.

Nationally, cancellations are spiking as buyers exercise caution. Locally, Columbus is seeing stabilized prices, rising inventory, and a more leveled playing field between buyers and sellers. If you’re thinking about making a move — whether buying, selling, or investing — understanding both the macro signals (cancellations, affordability) and local data (inventory, pricing trends) will help you position yourself for success.

Posted in Market Updates
Feb. 4, 2026

Winter Weather Puts the Brakes on the Mortgage Market

Winter Weather Puts the Brakes on the Mortgage Market

Winter doesn’t just slow down traffic and travel — it can also cool off the housing market. Recent winter storms across large parts of the U.S. have had a noticeable impact on mortgage activity, temporarily dampening demand as buyers and homeowners hit pause.

Mortgage Applications Take a Hit

During the final week of January, mortgage application activity dropped sharply. Purchase applications saw the biggest decline, signaling that many would-be buyers chose to wait out severe weather rather than push forward with home tours, inspections, and loan applications. Refinance activity also dipped, though to a lesser degree.

That said, the bigger picture tells a more balanced story. While week-to-week numbers fell, refinance demand remains significantly higher than it was at the same time last year. Homeowners are still paying attention to rates and looking for opportunities to lower monthly payments or restructure debt when conditions allow.

Storms and Scheduling Matter More Than Sentiment

Economists point to winter storms as a major driver behind the slowdown — not a sudden loss of interest in buying homes. When snow and ice disrupt daily life, housing activity is often one of the first things to be postponed. Add a holiday week into the mix, and short-term data can look more dramatic than it really is.

This kind of pause is typical for winter and doesn’t usually signal long-term trouble. Historically, activity tends to rebound once weather improves and buyers regain momentum.

Mortgage Rates Hold Steady

Despite the drop in applications, mortgage rates have remained relatively stable. Thirty-year fixed rates continue to hover in the low six-percent range, while fifteen-year fixed loans remain notably lower. The lack of major rate movement suggests the slowdown is driven more by logistics than affordability concerns.

Stable rates can actually work in buyers’ favor, giving them time to prepare without feeling pressured by rapid market shifts.

What This Means Going Forward

The recent dip in mortgage activity appears to be more about timing than fundamentals. Seasonal slowdowns, weather disruptions, and holiday weeks often distort short-term data. As winter fades and spring approaches, many analysts expect activity to pick back up.

For buyers, this could mean less competition in the near term. For sellers, it’s a reminder that patience is often necessary during the colder months. And for homeowners watching rates closely, the refinancing window — while quieter — is still very much open.

In short, winter may have chilled the mortgage market, but it hasn’t frozen it.

Source: Homes.com


Posted in Market Updates